Regulatory review and closing timetable
The Brazilian review comes after South32 shareholders approved the acquisition on October 15. Alcoa said it still expects to complete the transaction in the first half of 2027.
South32's announcement sets June 29, 2027, or an agreed later date, as the deadline for satisfying or, where permitted, waiving the closing conditions. Alongside the shareholder vote, those conditions include approvals from Australia's Foreign Investment Review Board and Australian Competition and Consumer Commission, and the Financial Surveillance Department of the South African Reserve Bank. Other international competition and regulatory clearances are also required, including approval under the South African Competition Act.
Mining, refining and smelting interests
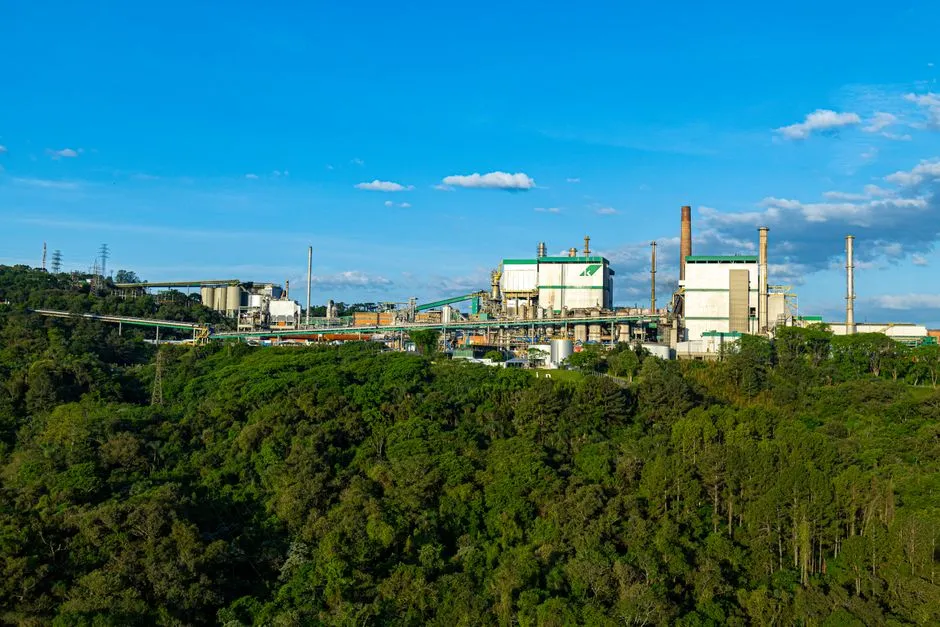
The Brazilian assets in the agreement are South32's interests in the Mineração Rio do Norte (MRN) bauxite mine and Alumar's alumina refinery and aluminum smelter. In Western Australia, Alcoa would acquire South32's interests in the Boddington bauxite mine and Worsley alumina refinery.
The South African portion includes the Hillside aluminum smelter and the property of the idled Bayside smelter. South32's Mozal aluminum smelter in Mozambique is not part of the sale.
Alcoa estimates that the acquisition would produce approximately $900 million in synergies on a net present value basis. Using calendar-year 2025 figures, it puts its pro forma production after closing at 3.2 million metric tons of aluminum and 14.8 million metric tons of alumina.
Purchase price and contingent payments
Alcoa announced the definitive agreement on June 30, 2026. The approximately $4.1 billion upfront payment consists of $3.1 billion in cash and about 17.0 million newly issued Alcoa common shares, valued at roughly $1.0 billion.
The companies have presented different enterprise-value figures. Alcoa puts the implied enterprise value at approximately $4.7 billion, including net debt. Separately, it agreed to provide a contingent value right worth up to $750 million, payable over four annual periods beginning July 1, 2026.
South32 describes the implied enterprise value as up to $5.6 billion. Its calculation includes the $3.1 billion cash payment, $1.0 billion in Alcoa shares, approximately $750 million in net debt and lease liabilities that Alcoa would assume, and up to $750 million in contingent cash payments linked to alumina and aluminum prices through 2030. South32 also said Alcoa would take on approximately $1.2 billion in related rehabilitation provisions.
Financing and South32's shareholder return
Alcoa completed two senior-note offerings on September 23, 2026: $1.5 billion carrying a 6.625% interest rate and maturing in 2034, and $1.1 billion carrying a 6.875% rate and maturing in 2036. It plans to combine the proceeds with cash on hand to fund the acquisition's approximately $3.1 billion cash payment. After completing the offerings, Alcoa terminated its remaining bridge financing commitments.
South32 plans to distribute half of the Alcoa shares it receives at closing to its shareholders, representing an initial return of approximately $500 million. The distribution would take the form of an in-specie, fully franked special dividend. South32 also expects its portfolio simplification to reduce annual overhead costs by about $125 million.