Rating rests on budget and easing tensions
The Financial Times reported on October 24 that Moody's had affirmed the rating the previous day. The decision brought unexpected relief as France faced sharply higher bond yields, a political impasse and nationwide demonstrations.
In leaving the rating unchanged despite slower growth and a larger deficit since its last review, Moody's assumed France would adopt a budget that reduces next year's deficit. It also expected borrowing costs and social tensions to ease somewhat in the coming months.
The budget remains unresolved. According to Fortune, the 2027 proposal would lower the deficit from 5.4% of gross domestic product to 5%, but political gridlock has kept it from passing. Moody's expects eventual adoption, potentially by decree if the National Assembly remains deadlocked.
Even with a budget in place, the agency forecasts a 2027 deficit of 5.2% of GDP. Fortune reported that Moody's attributed the shortfall against the proposal's target to growth below government projections and the political obstacles to carrying out spending cuts.
Prime Minister Sebastien Lecornu welcomed the rating decision on X, saying it contradicted pessimistic expert forecasts and showed creditors a way forward. He urged lawmakers to deliver a budget consistent with a 5% deficit target for this year.
Higher yields add to the debt challenge
Moody's said weaker growth and a wider deficit had already lifted France's debt burden above its earlier expectations. Bond yields had also climbed more quickly than the agency anticipated.
France's government debt is about 120% of GDP, placing it third in the eurozone behind Greece and Italy. This week, the yield on its 10-year government bond hit 5% for the first time since 2002. The gap over comparable German bunds reached roughly 1.7 percentage points, its widest since 2011.
The effect of those higher rates will take time to build. Fortune reported that Moody's put the average maturity of French debt at about 8.5 years, meaning borrowing costs would need to remain elevated for an extended period to substantially weaken debt affordability.
Still, Moody's projects debt will reach 122% of GDP next year and continue rising through the rest of the decade. According to Fortune, the agency said stabilizing the burden would require a "significant and sustained fiscal effort" beyond the presidential elections.
Protests and the election complicate fiscal plans
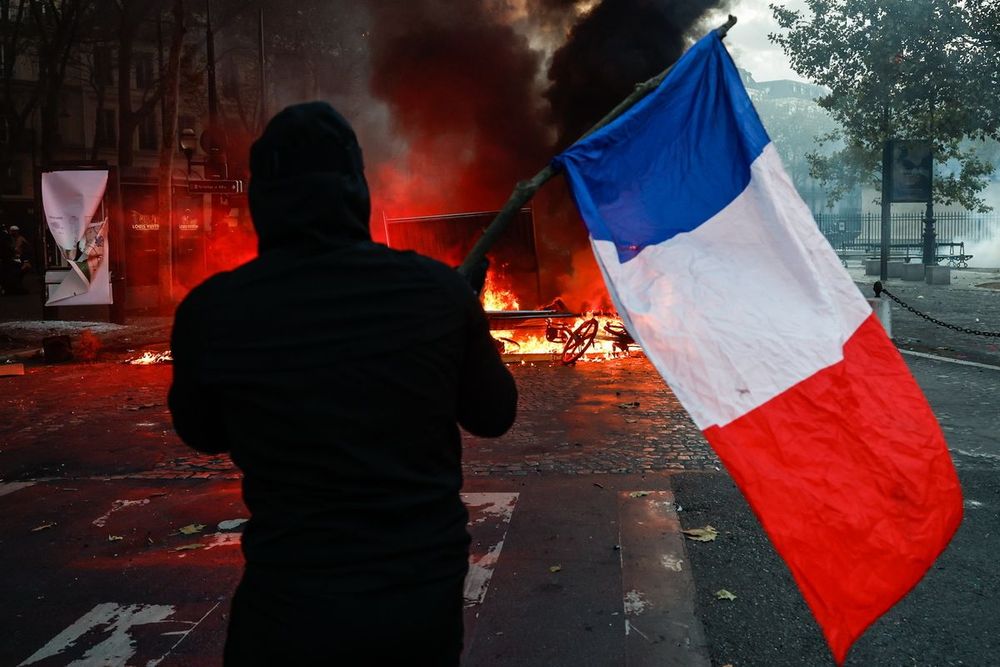
Moody's warned that widespread demonstrations could limit France's ability to repair its public finances. Fortune reported that protests had continued for more than a month and escalated into widespread riots in mid-October 2026. Similar demonstrations elsewhere in Europe form part of what has been called the "Oct. 17 Movement."
The next presidential election is due in spring 2027, with far-right and far-left candidates leading the race. According to Fortune, markets are losing confidence that either side would undertake the difficult measures needed to restore fiscal order.