Protests and competing explanations
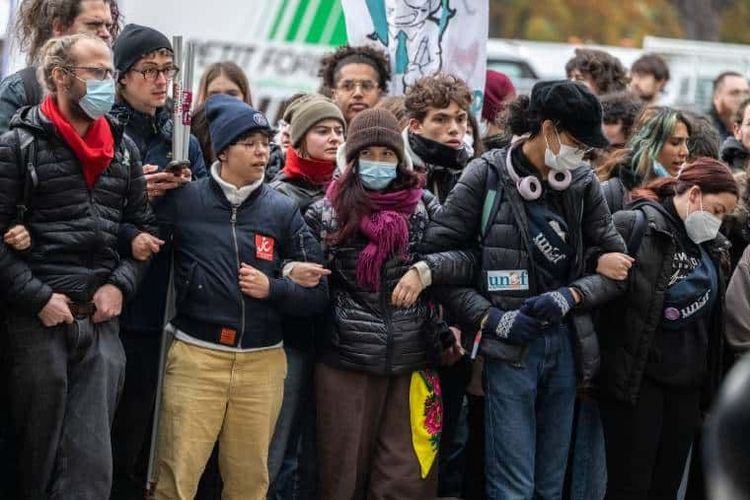
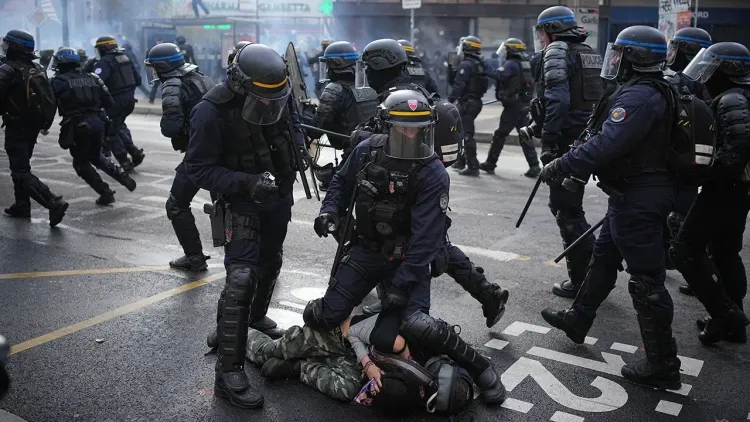
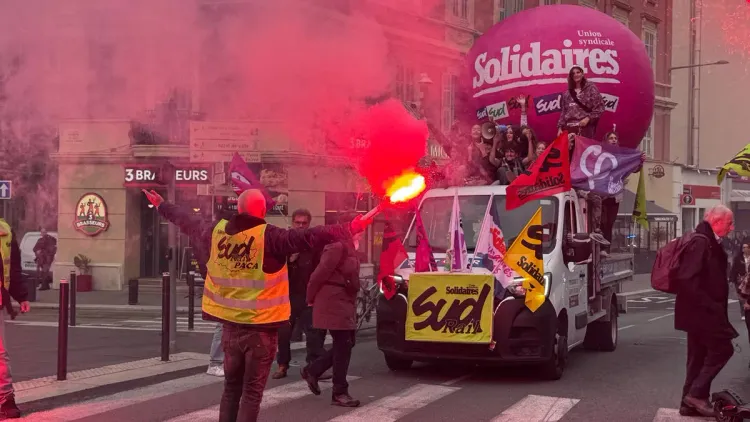
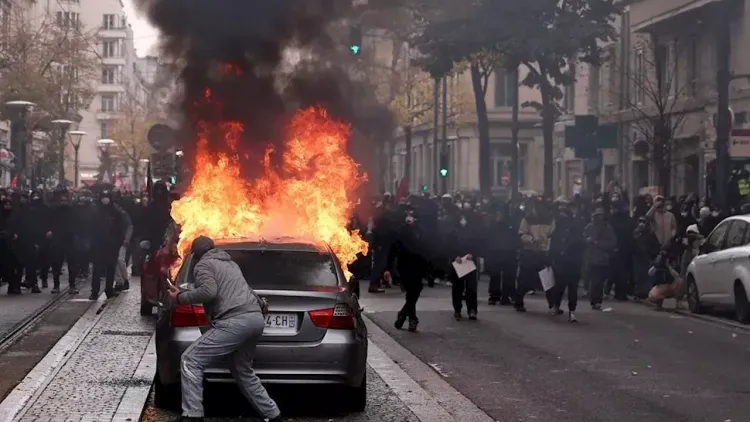
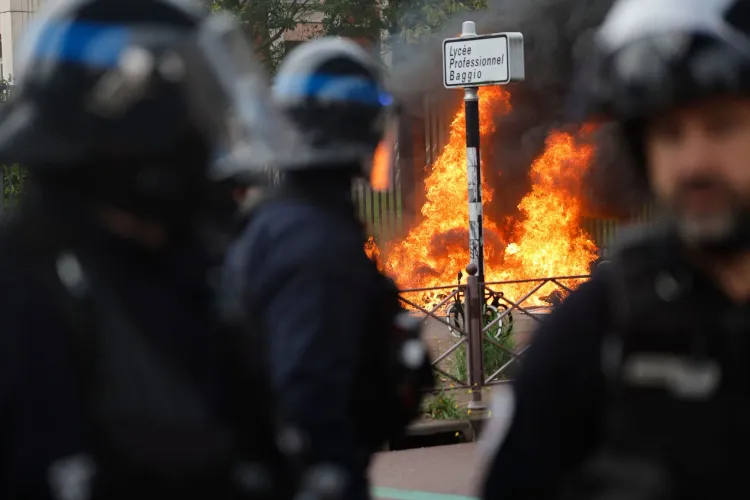
Between 550,000 and 800,000 demonstrators took to the streets across France on Oct. 17, following weeks of student protests that disrupted hundreds of schools. By that evening, fire had gutted a historic town hall in Limoges, and arrests totaled about 1,800, according to Brandon's account.
CNBC reported on Oct. 21 that French officials put the potential cost of damage from the weekend's rioting and looting in the hundreds of millions of euros.
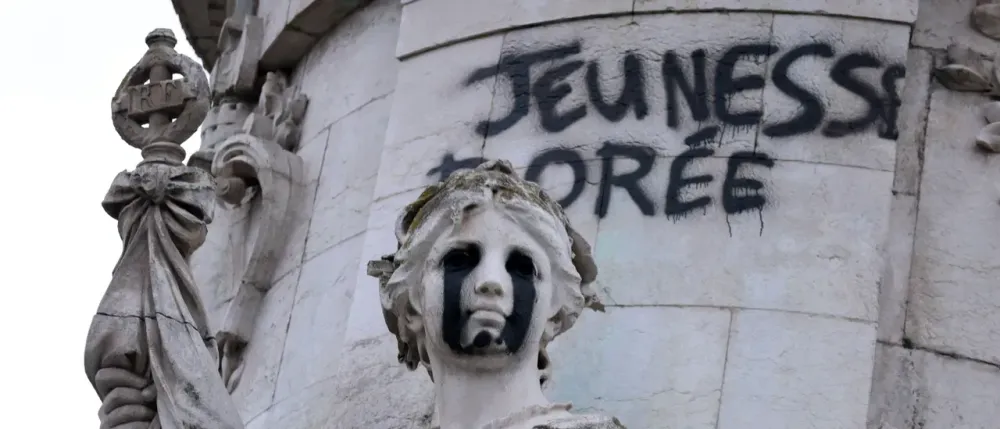
Trump urged France to close its borders. Brandon instead points to protesters' complaints about living costs, overstretched public services and limited prospects for the future. His argument is that unresolved financial strains, rather than immigration, are driving the unrest—and that the United States risks facing similar pressures.
France's budget and borrowing pressures
France entered the budget debate with national debt of about €3.6 trillion ($4 trillion), or 119% of gross domestic product, Al Jazeera reported on Oct. 20. That compares with 98% of GDP in 2019. Brandon writes that servicing the debt will cost roughly €74 billion in 2027, exceeding spending on either education or defense.
The government is proposing about €54 billion in savings and spending cuts in its 2027 budget bill, presented in early October, according to CNBC and Al Jazeera. The proposal aims to bring the deficit down to 5% of GDP next year from a projected 5.4% in 2026. France is already subject to the European Union's excessive deficit procedure, with the projected shortfall well above the bloc's roughly 3% reference limit.
Public spending amounts to about 57% of French GDP, a share exceeded only by Finland among OECD countries, according to Al Jazeera. Public pensions account for 14% of GDP. Meanwhile, economic growth is forecast at just 0.4% in 2026, compared with 0.9% in 2025.
Borrowing costs have reached a 24-year high. CNBC reported that France's benchmark 10-year government bond yield briefly exceeded 5% on Oct. 21, its first crossing of that threshold since 2002. The gap between French and German government bond yields widened to 1.7 percentage points, a premium last seen during the eurozone crisis of the early 2010s, according to the Observer.
Budget disputes have also brought down two prime ministers in less than a year, Brandon writes. Moody's nevertheless declined to downgrade France's government credit rating in October, the Observer reported. Prime Minister Sébastien Lecornu said the decision "thwarts the declinist forecasts" of debt skeptics.
Marine Le Pen, the frontrunner for the spring 2027 presidential election, said in October that she could lower the deficit below 3% of GDP within 18 months of taking office. CNBC reported that critics questioned the credibility of her proposed savings.
The U.S. comparison
Brandon's warning centers on the growing cost of U.S. federal borrowing. The Congressional Budget Office's February 2026 outlook projects annual net interest outlays of $2.1 trillion by 2036, up from more than $1 trillion in 2026. Over that period, debt held by the public is projected to rise from 101% to 120% of GDP, surpassing the previous record of 106% set just after World War II.
Brandon says the projected interest bill would absorb roughly half of Washington's tax collections. Interest spending already exceeds national defense spending, he notes. He describes the danger as a gradual loss of room to fund other government responsibilities, rather than a crisis arriving at one identifiable moment.
He also highlights a widening generational wealth gap. Citing the Federal Reserve's latest Survey of Consumer Finances, he writes that median household net worth increased about 38% from 2022 to 2025 among households headed by someone at least 75 years old. For those headed by someone under 35, it declined 23%. Americans age 55 and older hold about $140 trillion, roughly three-quarters of the country's net worth.
Brandon cautions against blaming older Americans, many of whom worked and saved over their lifetimes. His concern is the combination of declining wealth among younger households and the debt-service burden they are expected to bear.
A call for growth and compromise
Brandon advocates a long-term growth strategy built around more construction, worker training and opportunities to start businesses. He criticizes both major parties: one for cutting taxes while deferring responsibility for deficits, the other for promising additional spending without explaining how to pay for it.
He argues that fiscal restraint need not amount solely to benefit cuts. A sustainable approach, he writes, requires compromise and negotiation rather than appeals aimed only at each party's supporters. The commentary expresses Brandon's views, not the Daily Caller's official position.
With independents now the largest voting bloc and the midterm elections two weeks away, Brandon urges voters to press candidates on two points: their plans for economic growth and the concessions they would make to carry them out.